Foreclosure Bailout Loan vs Loan Modification: Which Is Better
TL;DR: When choosing between a foreclosure bailout loan and a loan modification, a loan modification wins if your lender agrees and you can afford the new payment. A foreclosure bailout loan wins when time is short, the lender says no, or the loan has matured. Both are better than losing the property at auction.
What Is the Difference Between a Foreclosure Bailout Loan and a Loan Modification?
A loan modification changes the terms of your current loan with your current lender. A foreclosure bailout loan is a new loan from a new lender that pays off the old one. We make foreclosure bailout loans, so we explain both options honestly.
What Is a Loan Modification for Mortgage Payments?
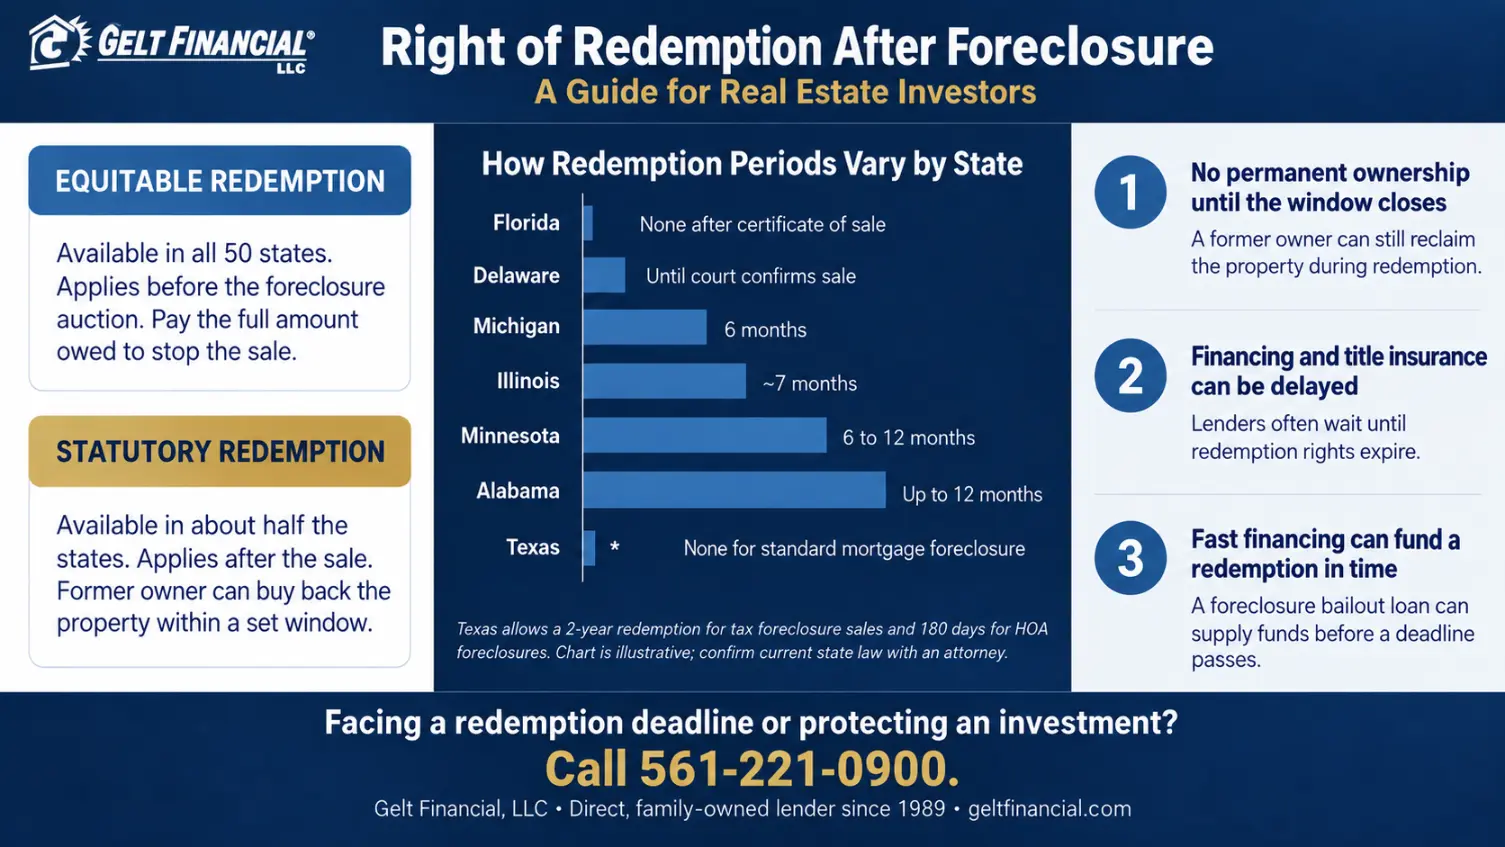
A loan modification, also called a mortgage loan modification or mortgage modification, permanently changes your mortgage terms. Your mortgage servicer collects your mortgage payments. It may lower the interest rate, stretch the term, or add missed payments to the loan amount. Lenders may modify a loan for borrowers who prove a hardship and can show an affordable payment. Those new mortgage terms replace your old ones, and the lender must approve them.
Loan Mod Facts
- The Home Affordable Modification Program is a government initiative for modifications.
- Loan modifications can suspend foreclosure proceedings during the process.
What Is a Foreclosure Bailout Loan?
Foreclosure bailout loans are short-term hard money loans that pay off your existing mortgage and stop the foreclosure process. The property serves as collateral. Approval rests on the property and its equity more than on your credit or income.
- Loan amounts for foreclosure bailout loans typically start at $500,000.
- These loans can refinance the entire mortgage or cover overdue payments.
- Approval for these loans can take 3-15 days.
- Foreclosure bailout loans often require substantial home equity and present higher financial risks.
- Loan-to-value ratios for bailout loans typically range from 50% to 65%.
Refinancing Is Another Option
Refinancing replaces your current mortgage with a new loan on better terms, which can lower your monthly payment. The catch is timing: most lenders want you current on payments first. That makes refinancing a fit for borrowers who are still on time, not for most investors already in default. Many programs also target owner-occupied primary residences, so check eligibility early.
Refi Facts
- Homeowners must be current on their mortgage to qualify for refinancing.
- Refinancing can lower monthly mortgage payments for eligible homeowners.
- The Homeowner Affordability and Stability Plan was signed in February 2009.
- A short refinance can help homeowners with negative equity.
How Do a Foreclosure Bailout Loan and a Loan Modification Compare?
| Factor | Loan modification | Foreclosure bailout loan |
|---|---|---|
| Who approves it | Your current lender or servicer | A new lender, based on the property and equity |
| What it does | Changes the terms of your current mortgage | Pays off your current mortgage with a new loan |
| Speed | Depends on the servicer’s review | Built for short deadlines |
| Credit and income | Needs proof of financial hardship and income | Focuses on property value and equity |
| Cost | Lower payment, but missed payments often add to the balance | Higher interest rates, points, and fees |
| Foreclosure in progress | May not stop the case on its own | Payoff ends the case |
| Maturity default | Works only if the lender agrees to an extension | Pays off the matured loan |
| Best fit | Temporary setback and a willing lender | Close sale date, denial, or maturity default |
Can You Get a Loan Modification on Investment Property?
Sometimes. Freddie Mac lists investment property as eligible for its Flex Modification. Fannie Mae’s version works the same way: it adds missed payments to the balance, can lower the rate, and extends the term. Both programs replaced HAMP, which grew out of the 2008 foreclosure crisis.
Both programs cover only loans that Fannie Mae or Freddie Mac own or back. The loan also usually must be at least 60 days behind or close to default. Where the program falls short:
- Private, bridge, and hard money loans fall outside these programs, so any change is the lender’s choice.
- Most online advice targets homeowners with a primary residence, and many loss mitigation protections target them. Investors often have fewer rights.
- A payment default and a maturity default need different fixes. A maturity default means the loan came due and you can’t pay it off, so a modification becomes an extension the lender may refuse.
Check your notice of default to see which default you have.
Which Is Faster, a Foreclosure Bailout Loan or a Loan Modification?
A foreclosure bailout loan is usually faster because nobody has to agree to change your existing loan. A modification depends on the servicer’s review, and foreclosure proceedings may keep moving while you wait. See how quickly we can close.
Which Costs More?
A foreclosure bailout loan costs more up front. Expect higher interest rates, points, and fees, which we break down in our guide to rates, points, and fees. We are honest about every charge and add no hidden fees.
A modification aims for a payment reduction, so it can cost less up front. It often adds missed payments to the loan amount and stretches the term, so you pay more interest over time.
When Does a Loan Modification Make Sense to Avoid Foreclosure?
- Your lender is willing, and the loan qualifies.
- Your financial problems are temporary, such as a job loss or a medical emergency, and you can afford the new monthly payment.
- The sale date is far off. Some court-driven foreclosure proceedings run for years, according to Cornell Law School’s Legal Information Institute.
Ready to move fast? Call us at 561-221-0900 for a free quote.
When Does a Foreclosure Bailout Loan Make More Sense?
- The sale date is close.
- The servicer denied your request or won’t respond.
- The loan matured.
- The property has equity.
Gelt Financial is a family-owned direct lender. We’ve closed more than 10,000 loans since 1989 in 38 states. Our lending services cover only residential investment property, like a rental house, and commercial property, never an owner-occupied primary residence.
Most lenders review income and credit first. We start with the property and its equity. Our team understands foreclosure deadlines, and we send the funds to your lender at closing. A bailout loan then works as a bridge until you sell or refinance. See how to qualify for a bailout loan.
Negative equity changes the math. If you owe more than the property is worth, a bailout loan usually won’t work. Short sales, a deed in lieu, or a modification may fit better. Falling home prices can create negative equity fast.
Tell us about every lien. Your first mortgage, second mortgages, and any home equity line all count as debt against the property.
Have questions? Call us at 561-221-0900, and our team will help.
Can You Try a Loan Modification and a Foreclosure Bailout Loan at the Same Time?
Yes. Ask your servicer for a modification in writing, and line up a bailout loan as your backup. Mortgage brokers can help you shop for a bailout lender, but ask whether they understand foreclosure deadlines. Never let the sale date pass while you wait. Follow this plan:
- Confirm your default type and your sale date.
- Ask the bank for a payoff amount.
- Ask your servicer in writing about loss mitigation, including a modification or extension, and ask for better terms if you get an offer.
- Gather the property, equity, and lien details a bailout lender needs.
- Set a firm decision date, then act.
There is no single best solution for every borrower. The right choice is the one in your best interest, based on your financial situation and your deadline. If you’re facing foreclosure and struggling with mortgage payments, acting early gives you more ways to prevent foreclosure and avoid foreclosure on the property. Talk to a real estate attorney before you sign anything. We’re not a law firm, and this isn’t legal advice.
Apply online at GeltFinancial.com or call us today to get started.
Key Takeaways
- A loan modification changes your current mortgage. A foreclosure bailout loan replaces it with a new loan.
- Fannie Mae and Freddie Mac programs can cover investment property, but only on loans they own or back.
- Private and hard money loans depend on the lender’s choice.
- A bailout loan is usually faster and costs more up front. A modification can raise total interest over time.
- Negative equity can rule out a bailout loan.
- You can pursue both options, but never let the sale date pass.
What Do People Ask About a Foreclosure Bailout Loan vs a Loan Modification?
Does a loan modification stop foreclosure?
Not automatically. On investment property, the lender may keep the case moving while it reviews your request. Ask for any pause in writing, and keep a bailout loan ready as your backup.
Can you get a foreclosure bailout loan if a lender denies your loan modification?
Yes. A denial doesn’t block a bailout loan. The sooner you contact us, the more time we have before your sale date.
Is a foreclosure bailout loan more expensive than a loan modification?
Usually, up front. Compare the total cost over the time you plan to hold the loan, since a modification can raise total interest by stretching the term.
Does a loan modification hurt your credit?
The missed payments before a modification already do the damage. The modification itself can still show on your report, so ask a credit professional. A completed foreclosure typically stays on your report for years.
Can you get a loan modification on a loan that already matured?
Only if the lender agrees to extend it. A maturity default makes the full balance due, so lenders often want a payoff, not a new payment plan. Ask early, and line up a payoff option.
Foreclosure bailout loan vs loan modification: which is better depends on your lender, your equity, and your sale date.
Call us at 561-221-0900 today! Gelt Financial is ready to discuss your financing needs on commercial or investment real estate.